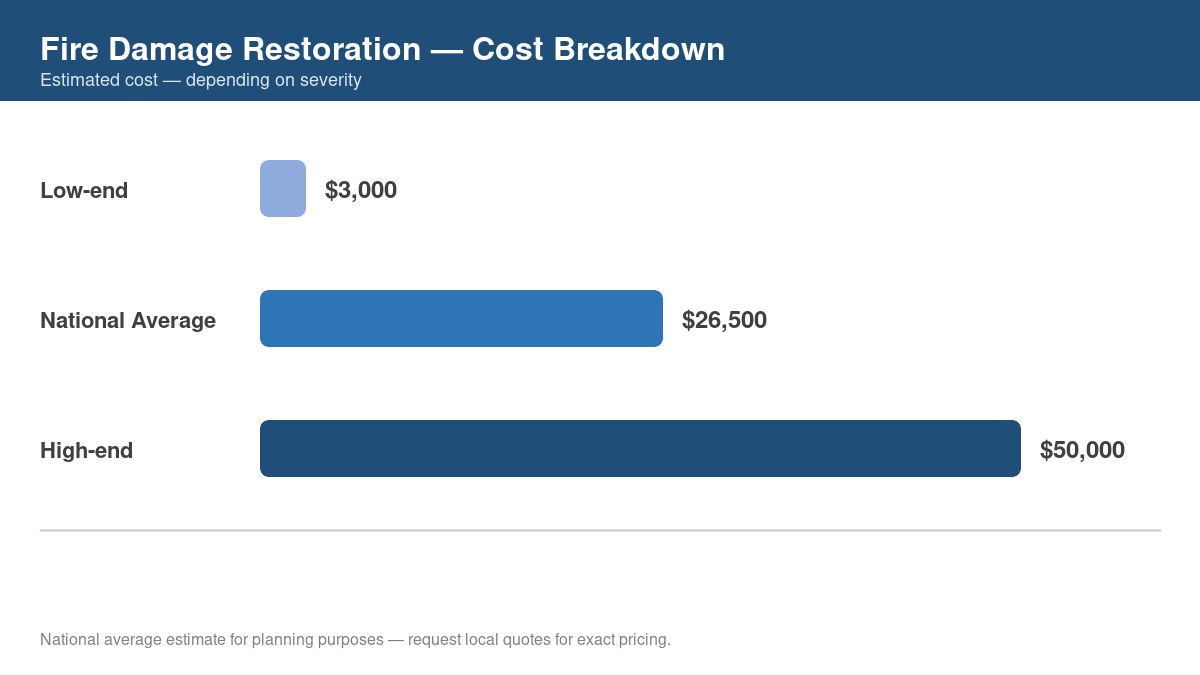
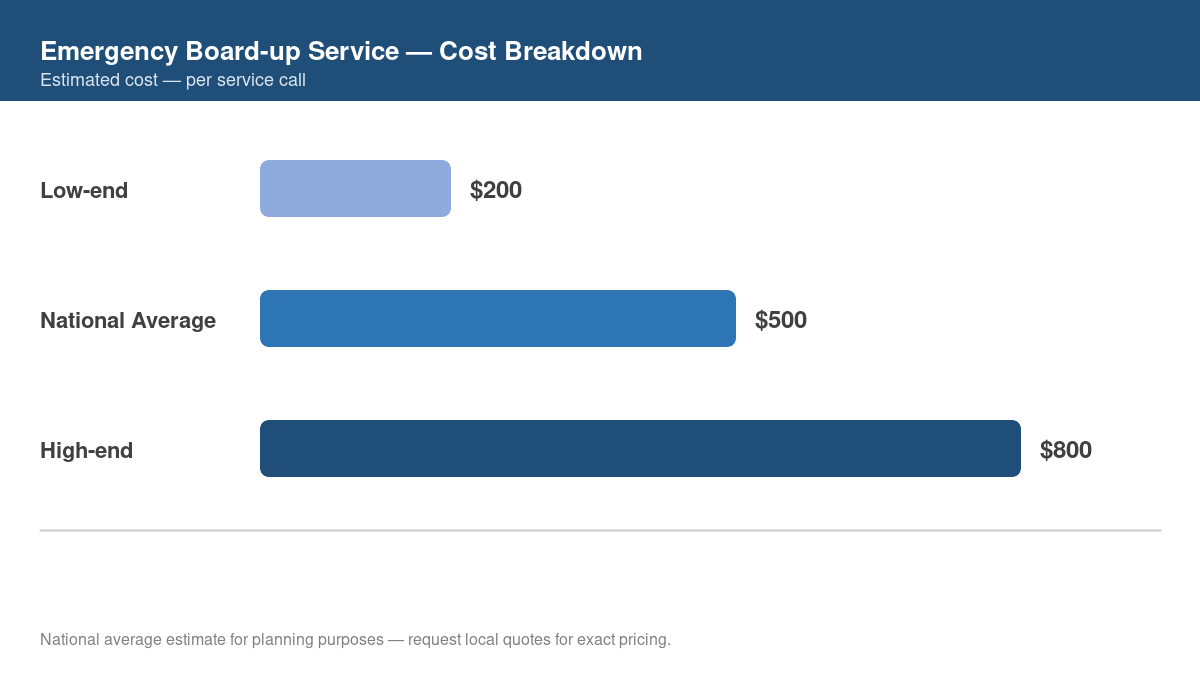
The cost range listed here for emergency board-up service is $200 to $800 per service call. Use it as a budget estimate and request a written quote for your home. Materials, local labor rates, and the amount of work affect the price.
Local labor rates, material availability, access, and permit fees affect the quote. Ask contractors to price the same scope so you can compare their estimates.
What is the estimated cost?
The listed estimate is $200–$800 per service call. Get itemized local quotes before setting your budget. Ask which work and materials each estimate includes.
What affects the price?
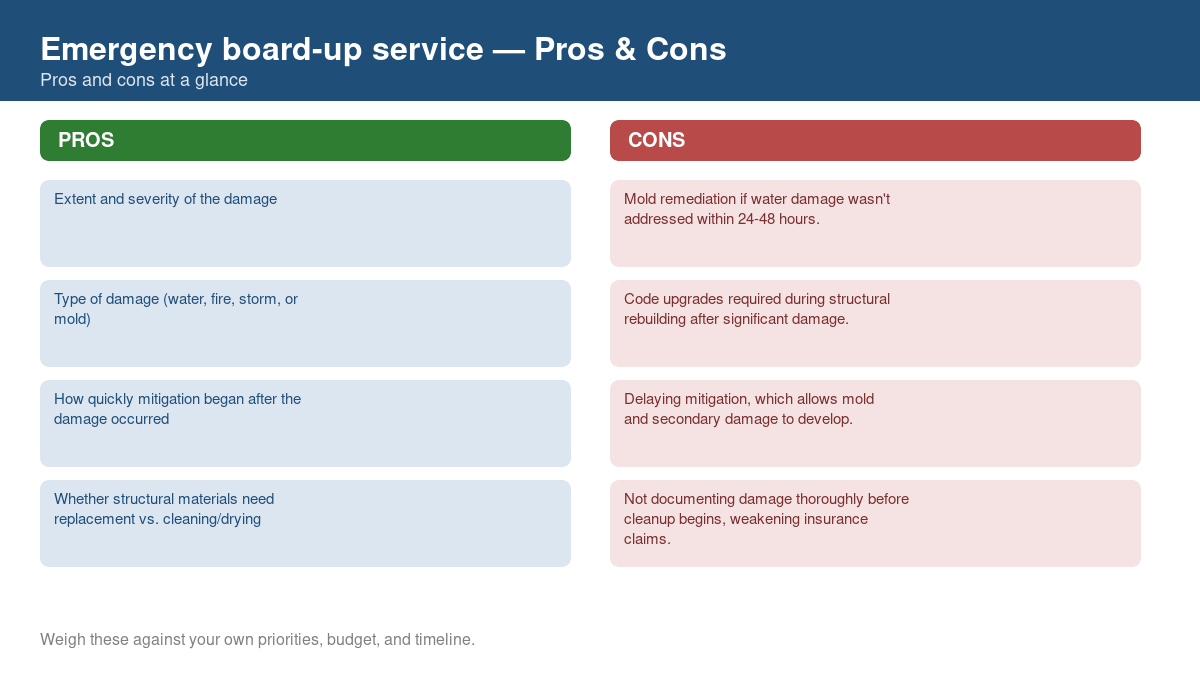
- Extent and severity of the damage. More extensive damage requires more materials, labor, and equipment to fully restore.
- Type of damage (water, fire, storm, or mold). Fire damage typically costs more to restore than water damage due to smoke penetration and structural concerns.
- How quickly mitigation began after the damage occurred. Faster mitigation response significantly reduces the extent of secondary damage and total cost.
- Whether structural materials need replacement vs. cleaning/drying. Full material replacement costs more than cleaning and drying salvageable materials.
- Insurance coverage and deductible amount. Your deductible and coverage terms determine how much of the cost you'll pay out of pocket.
- Emergency/after-hours service needs. Emergency and after-hours response typically carries a premium over scheduled daytime service.
Which costs might the estimate exclude?
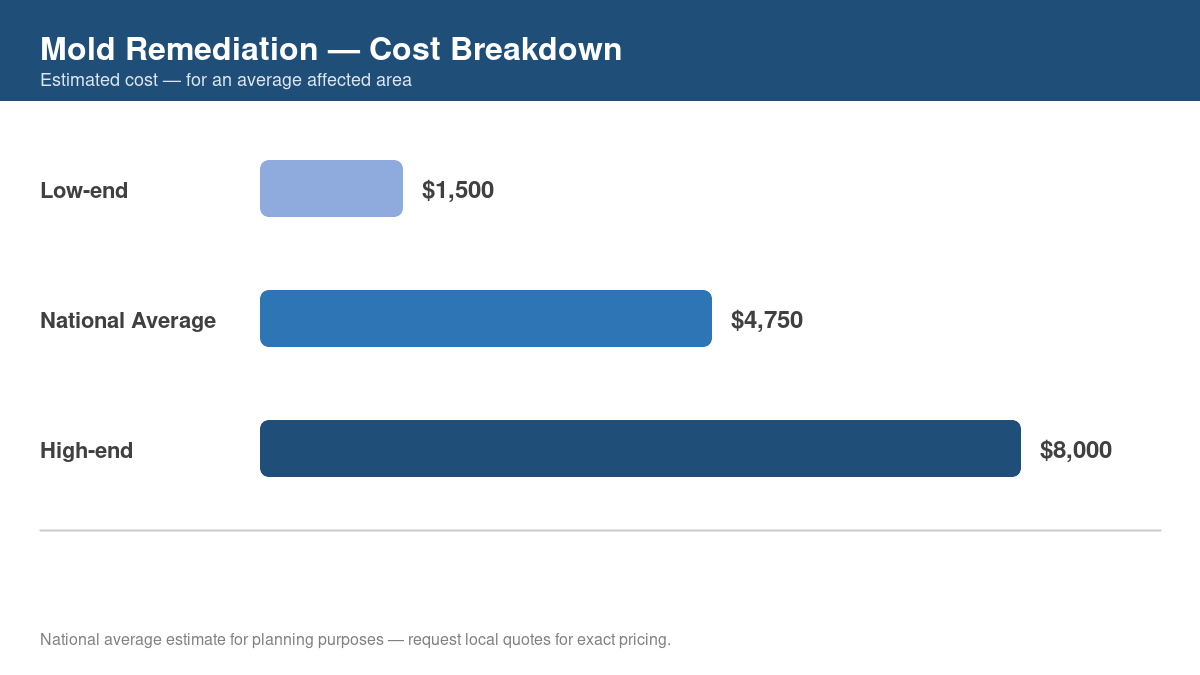
- Mold remediation if water damage wasn't addressed within 24-48 hours.
- Code upgrades required during structural rebuilding after significant damage.
- Content cleaning or replacement for damaged furniture and belongings.
- Temporary housing costs if the home is uninhabitable during restoration.
Should you hire a contractor?
Some smaller-scope work on emergency board-up service can be handled by an experienced DIYer, but most of this job involves code-sensitive systems, specialized tools, or safety risk, so hiring a licensed professional is the safer choice for most homeowners. A failed DIY attempt on code-regulated work can end up costing more than hiring a professional from the start, once you factor in corrective repairs and re-inspection.
How can you reduce the project cost?
- Act immediately when damage occurs. Faster mitigation significantly reduces total restoration cost.
- Document everything with photos before cleanup begins to support your insurance claim.
- Get a second opinion on major restoration scopes before authorizing extensive demolition.
- Ask your restoration company to work directly with your insurance adjuster to avoid duplicate assessments.
How can you get a detailed quote?
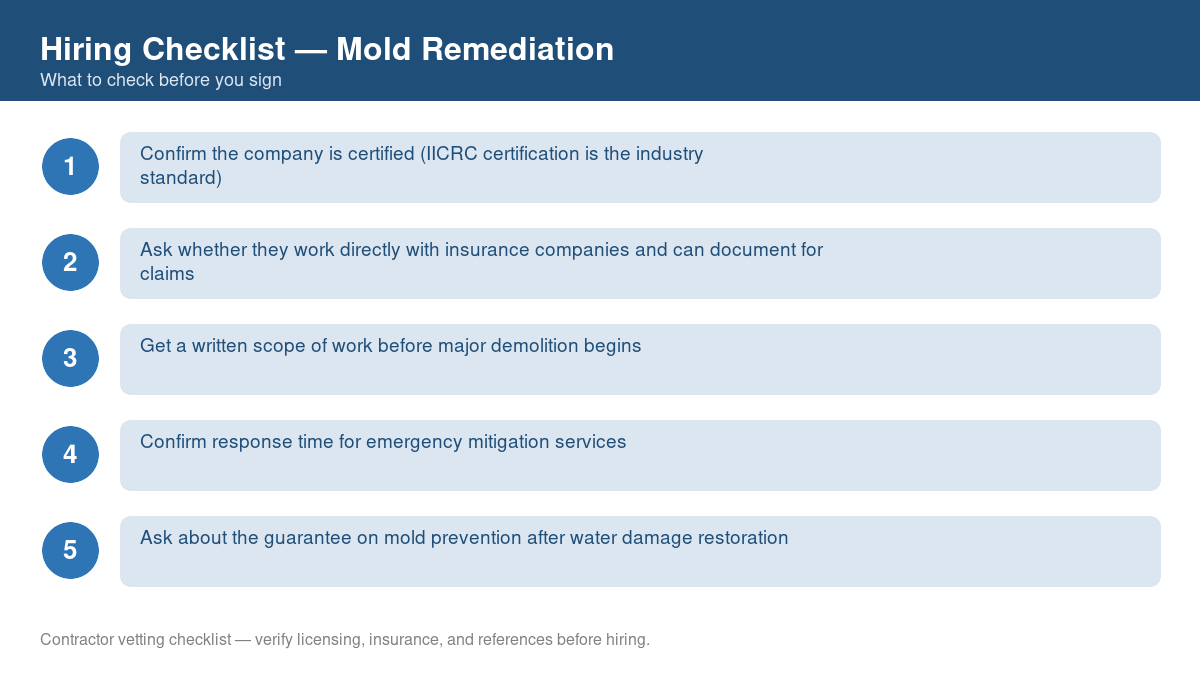
- Confirm the company is certified (IICRC certification is the industry standard).
- Ask whether they work directly with insurance companies and can document for claims.
- Get a written scope of work before major demolition begins.
- Confirm response time for emergency mitigation services.
- Ask about the guarantee on mold prevention after water damage restoration.
What other questions should you ask?
What maintenance information should you request?
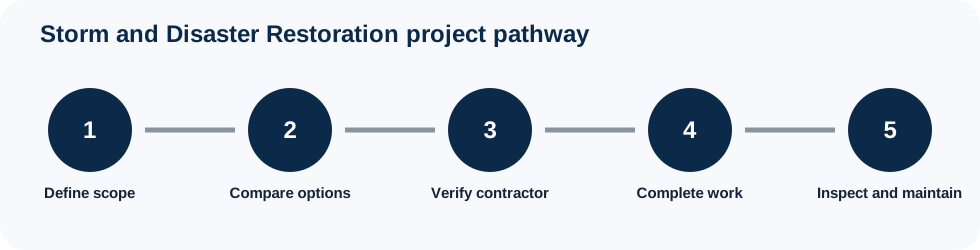
Ask for written care instructions and warranty terms. Keep a record of inspections, maintenance, and repairs.
How should you plan ongoing care?
- Inspect the completed work at the intervals recommended in the care instructions. Report damage or recurring problems promptly.
- Keep the invoice, warranty, permit records, and maintenance instructions together.
- Follow the product's maintenance instructions and check the warranty conditions.
- Address small problems as soon as you notice them rather than waiting for a bigger, more expensive failure.
How Emergency board-up service Compares to Other Storm & Disaster Restoration Projects
Related work may include smoke damage cleaning, flood damage cleanup, and storm damage repair. Ask whether any of these jobs need to be coordinated with this project. Have the contractor price combined and separate work if both are practical.
How should you plan project financing?
If you borrow to pay for the work, include interest and fees in the budget. Compare repayment terms before choosing a loan.
Which financing options should you compare?
- Cash or savings: No loan interest, but the payment reduces the cash available for other expenses.
- Home equity loan or HELOC: Your home secures the debt. Compare interest rates, fees, and repayment terms.
- Personal loan: Check whether the loan is secured or unsecured, then compare the rate, fees, and total repayment cost.
- Contractor or manufacturer financing: Check the promotional period, fees, and interest charged if you do not repay the balance by the deadline.
How do you compare borrowing costs?
Compare the interest rate, fees, repayment term, and total amount you will repay. A longer term can lower the monthly payment while increasing the total interest cost.
What should a complete estimate include?
- A detailed scope that identifies the work, quantities, and exclusions.
- Material brands, grades, and quantities, with substitutions agreed in writing.
- Who obtains any required permits and pays the fees.
- Cleanup and disposal work, including any separate charges.
- Deposit amount and later payments, with the work required for each payment.
- Written warranty terms, including coverage, exclusions, and duration for materials and labor.
What else should you ask before hiring?
- Can I negotiate the price on emergency board-up service? Ask whether the price is negotiable. If the contractor offers a discount, confirm that the scope, materials, and warranty stay the same.
- What should I do if I'm unhappy with the finished work? Describe the problem to the contractor in writing and ask for a response by a stated date. Keep photographs and records. Check the contract's dispute process and the complaint options available in your state.
- How do I verify a contractor's license and insurance? Ask for the license number and check it with the agency responsible for that trade in your area. Verify insurance coverage separately with the insurer.
- Is it normal for a emergency board-up service quote to change after the initial visit? Ask what changed after the inspection. Get the revised scope, price, and reason for the change in writing before agreeing to additional work.
How should you check insurance coverage?
Ask for evidence of the contractor's insurance and confirm coverage with the insurer. Check whether workers' compensation coverage is required for the crew. Ask your own insurer whether the planned work affects your policy.
What ongoing costs should you consider?
Include maintenance, repairs, and eventual replacement when comparing costs. Ask what upkeep the proposed materials or equipment need and which costs the warranty covers.
Ask each contractor for the maintenance schedule and expected service life of the proposed materials or equipment. Request the written product specifications and warranty terms.
How do you check the contractor's work history?
Read recent reviews and check how the contractor handled complaints. Contact references for similar work completed recently. Ask how the contractor records changes, prices extra work, and resolves disputes. Put those procedures in the contract.
Which contract terms should you understand?
Check these terms when reading the contract. Ask the contractor to explain any wording that leaves the scope, payment, or completion requirements unclear.
What do these contract terms mean?
- Change order: A written change to the contract. Agree on the additional or reduced work, price, and schedule before approving it.
- Punch list: Unfinished work or defects recorded during the walkthrough. Agree on when the contractor will resolve each item.
- Lien waiver: A document that waives lien rights under specified conditions. Check which payment it covers and whether it is conditional or unconditional.
- Retainage: Part of a payment held until the contract's release conditions are met. Specify the amount and conditions in the contract.
- Substantial completion: The stage when the work can be used for its intended purpose. Check the contract for the definition and any payment or warranty dates tied to it.
How should you plan for disruption?
Ask which rooms or services will be unavailable during the work and for how long. Confirm any planned utility interruptions, dust controls, and daily cleanup.
Keep children and pets away from the work area. If you will lose access to a kitchen, bathroom, or essential service, ask when it will be usable again and plan around that schedule.
Request written estimates from local contractors for the work you need.
Get Free QuotesProject planning
Check the scope, site conditions, and local requirements before setting the budget and schedule.
Project delivery options compared
| Approach | Best suited to | Primary trade-off |
|---|---|---|
| DIY or owner-managed | Low-risk cosmetic work within the homeowner’s skill level | Owner assumes safety, quality, scheduling, and code risks |
| Specialty contractor | A clearly defined trade-specific scope | May require the homeowner to coordinate other trades |
| General contractor or design-build team | Complex projects involving several trades or structural changes | Higher management cost, with centralized coordination |
Typical project timeline
| Phase | Typical planning window |
|---|---|
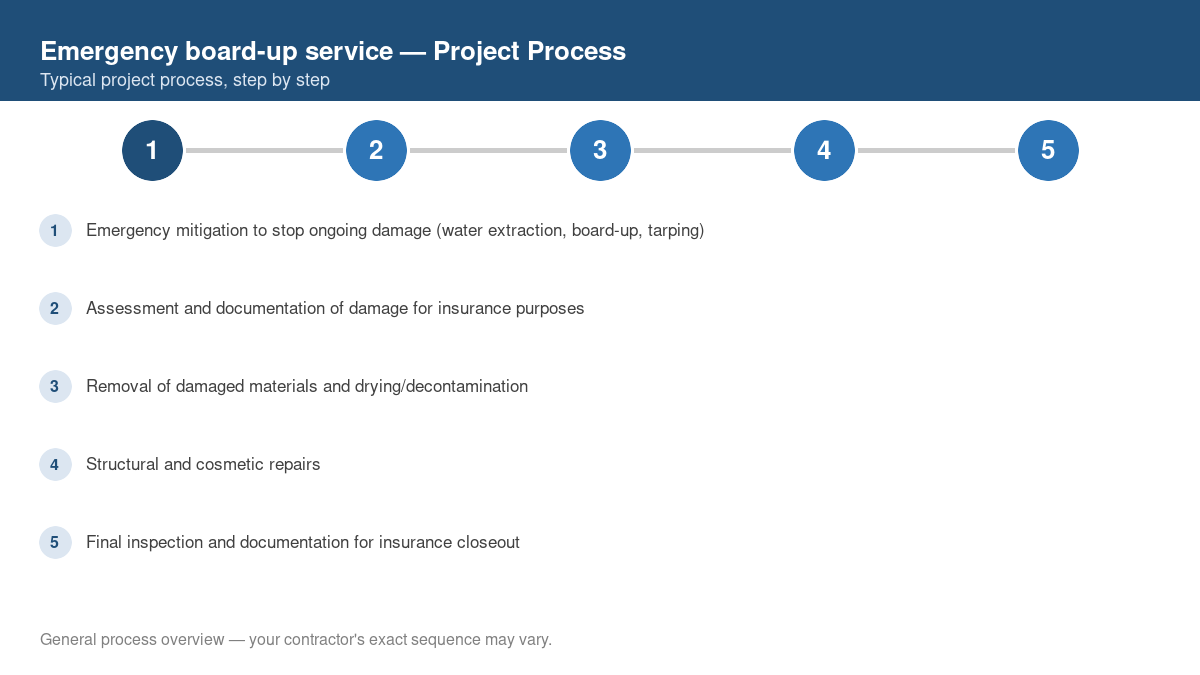
| Assessment and scope | 1-3 days |
| Selections and written quote | 2-14 days |
| Permits and scheduling | Varies by location |
| Active project work | 1 day to several weeks |
| Inspection, cleanup, and handoff | 1-3 days |
Benefits and limitations
Potential benefits
- Improves function, safety, or appearance
- Can address deferred maintenance before it spreads
- Creates an opportunity to document warranties and future upkeep
Potential trade-offs
- Upfront cost may change when hidden conditions are found
- Work can disrupt normal use of the area
- Permits, inspections, and material lead times may affect scheduling
Project stages